The short answer
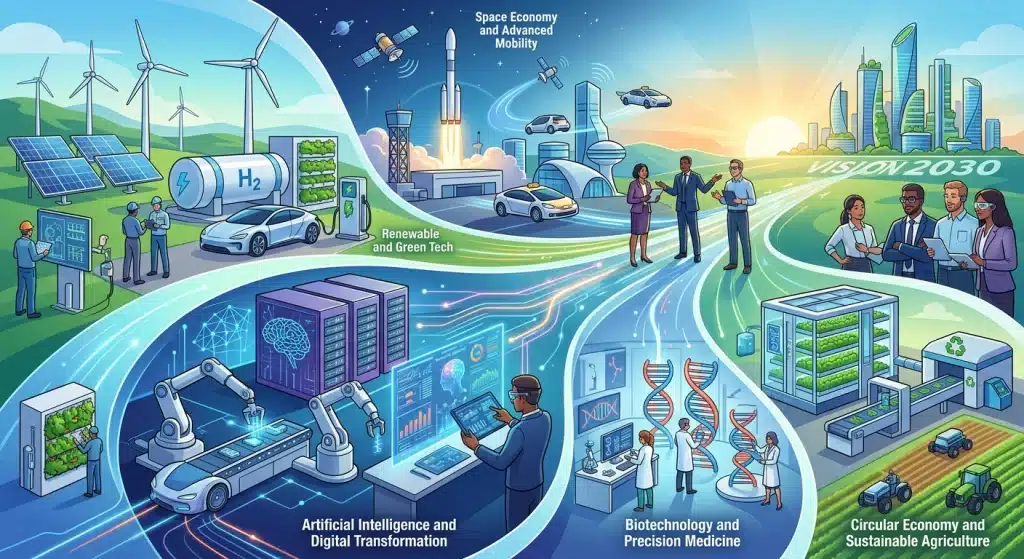
Vision 2030 venture opportunities are strongest where the state is opening a sector to private operators and where local-content rules create gaps for new Saudi companies. That includes tourism and sports, healthcare, renewable energy, logistics, manufacturing, fintech and AI. The 2026 to 2030 phase puts more weight on the private sector. Corporates that want to build, not only invest, should pick sectors where they hold an advantage such as customers, data or distribution, and fund each venture in stages.
Where Vision 2030 stands in 2026
Secondary sources report that 93% of Vision 2030 key performance indicators met or exceeded their 2025 annual targets, and describe the 2026 to 2030 phase as one with a bigger role for the private sector. We could not read the official annual report, so check it before quoting the figure.
The Public Investment Fund (PIF) approved its 2026 to 2030 strategy on 15 April 2026. It is organized around six ecosystems: tourism, travel and entertainment; urban development; advanced manufacturing and innovation; industrials and logistics; clean energy, water and renewables infrastructure; and NEOM. PIF reports assets above $900 billion, more than $199 billion invested in new Saudi projects in 2021 to 2025, and more than $157 billion spent with the local private sector in 2021 to 2024. The release gives no numeric targets for 2026 to 2030.
Press reports also point to re-phasing. AGBI reported in July 2026 that PIF has reduced spending on some giga-projects since 2024 and expects capital spending to fall by about 15% this year, while AI data centers, a green hydrogen plant and the Oxagon port continue. It reported project awards up about 54% year on year to $30 billion in June 2026. These are press reports, not official figures. The practical lesson for a corporate is to plan on staged delivery and to avoid depending on a single project timetable.
Sector by sector: where venture gaps appear
The table summarizes each sector with the latest figures we could verify and the kind of venture it may support. The venture ideas are TURN8’s own reading of the data, not forecasts. Several figures are from 2024 or earlier and are marked as such.
Table 1. Figures are dated; tourism, healthcare, manufacturing and fintech are from 2025 to 2026, and logistics and mining are older. Sources are listed at the end.
We did not find verified, current figures for artificial intelligence capacity or for the SDAIA program, so AI is covered separately in our guide to an AI studio for GCC corporates.
Local content creates gaps that new companies can fill
Clyde & Co (1 September 2026) describes how local content shapes government buying. Government bodies generally follow a Mandatory List of National Products, and foreign products compete as if priced 10% higher than national ones. Some tenders require a committed local-content percentage, with reporting, and a new Government Tenders and Procurement Law was approved on 5 August 2026.
A February 2026 report in Gulf News says the rule that barred government contracts to foreign firms without a Saudi regional headquarters has been relaxed, with exceptions through the Etimad platform, for example when a bid is the only compliant bid or is priced at least 25% below the next. Each rule affects who can supply government projects, and each can leave a gap that a new Saudi company can fill. We explore this in our article on the local-content venture formation gap.
What the venture funding data says
Saudi startup funding was strong in 2025. MAGNiTT reported $1.72 billion, up 145% year on year, across 257 deals, and Saudi Arabia ranked first in MENA for deal activity for the first time. The first half of 2026 was weaker. MAGNiTT and SVC report funding down 74% and deals down 41% year on year, with Saudi Arabia’s share of MENA funding falling from 49% to 16%. Other sources give different dollar totals for the half, so we quote only the direction and MAGNiTT’s percentages.
The Jada Fund of Funds reports SAR 3.7 billion in commitments across 47 funds and support for 758 small and medium enterprises in its 2025 annual report. The report does not mention corporate ventures. This suggests corporate-built ventures are not yet a focus of the program, which is an observation and not a finding.
How a corporate can choose a sector (TURN8 view)
The checks below are TURN8’s own suggestions and are not a published framework.
Table 2. TURN8 editorial checklist.
Corporates that want to turn a sector gap into a company can read our guide to corporate venture building in Saudi Arabia and our posts on the energy transition opportunity, the FIFA 2034 venture opportunity and the healthcare workforce gap.
How TURN8 works with GCC corporates
TURN8 is a venture operating partner for GCC corporates and sovereign-linked institutions. It builds ventures with staged capital, evidence gates at every milestone and objective go, hold or stop decisions. A corporate can have TURN8 design, build and operate (Operate For You), work alongside its teams (Operate With You) or have TURN8 build the capability and hand over operations (Build to Own). Learn about venture building, the TURN8 method and our work as venture builders in Saudi Arabia.
Table 2. TURN8 editorial checklist.
Looking at a Vision 2030 sector?
TURN8 can help test the opportunity against your assets before you commit capital. Request a Private Briefing or Discuss a Mandate.
Frequently Asked Questions
Which Vision 2030 sectors offer venture opportunities?
Sectors where the state is opening activity to private operators include tourism and entertainment, sport and events, healthcare, renewable energy, logistics, manufacturing, fintech, education and mining. Which suits a corporate depends on the assets and customers it already has.
What is the PIF 2026 to 2030 strategy?
PIF approved its 2026 to 2030 strategy on 15 April 2026. It is organized around six ecosystems: tourism, travel and entertainment; urban development; advanced manufacturing and innovation; industrials and logistics; clean energy, water and renewables infrastructure; and NEOM. The release gives no numeric targets.
How does local content create venture opportunities in Saudi Arabia?
Government buyers generally follow a Mandatory List of National Products, and foreign products compete as if priced 10% higher. Some tenders require a committed local-content percentage. These rules can leave gaps that new Saudi companies can fill.
Is Saudi startup funding growing?
Funding was strong in 2025, with MAGNiTT reporting $1.72 billion, up 145%, across 257 deals. The first half of 2026 was weaker, with funding down 74% and deals down 41% year on year according to MAGNiTT and SVC. Sources differ on dollar totals for the half.
Are Vision 2030 giga-projects still going ahead?
Press reports describe re-phasing, with reduced spending on some projects and continued progress on others such as AI data centers, a green hydrogen plant and the Oxagon port. These are press reports and not official figures, so corporates should plan on staged delivery.
How should a corporate pick a sector to build in?
Start with where it holds an advantage such as customers, data or distribution. Then check policy support, timing, the age of the market data and whether the first stage can be funded without relying on one large project.
Important information
This article is general information about corporate venture building and is not financial, investment, legal or tax advice. Figures are taken from the sources listed below and were checked in October 2026; they may change. Examples and thresholds are illustrative unless stated. Past results do not predict future performance.
Sources
- Public Investment Fund, PIF Board approves PIF 2026 to 2030 strategy (15 April 2026)
- Skift, Saudi Arabia reports 5% gain in 2025 visits (23 January 2026)
- AGBI, New contract advances work at Riyadh Expo 2030 site (April 2026)
- U.S. Commercial Service, Saudi Arabia healthcare country commercial guide (11 May 2026)
- SAB, Renewables business insight (February 2026)
- Asharq Al-Awsat, General Education System (17 August 2026)
- Clyde & Co, Local content in Saudi Arabia (1 September 2026)
- Gulf News, New rule: Saudi Arabia reverses restriction and allows foreign companies in government projects (21 February 2026)
- Arab News, MAGNiTT 2025 Saudi venture funding (12 January 2026)
- MAGNiTT and SVC, H1 2026 Saudi Arabia venture capital report
Partner · TURN8
Ahmed Hassan is a Partner at TURN8, the venture operating partner for GCC corporates and sovereign-linked institutions. He leads the firm’s corporate venture offerings, the venture studios, accelerators, and CVC platforms. TURN8 builds and runs for its partners, and owns go-to-market across every engagement.